Srishti Magoo
Excellent experience with TaxCaller for filing my & my family members ITR returns. The entire process was smooth, quick and hassle-free. They are professional, knowledgeable and guided me through every step with patience.
LLP registration online under the LLP Act, 2008, with DSC, DIN, name approval, FiLLiP, PAN, TAN and the Form 3 agreement handled by our tax experts.
Content updated 21 Nov 2026
Register your LLP
23 onlineHow we work
Online · Call · WhatsApp
Quick answer
LLP registration is the process of forming a Limited Liability Partnership with the MCA under the LLP Act, 2008, using the RUN-LLP and FiLLiP forms. You need two partners, two designated partners (one resident in India), DSCs and a registered office. It usually takes 10 to 15 working days. TaxCaller's fee starts at ₹2,999 + GST; government fees are extra.
Two partners who want their LLP registered with the agreement filed
₹2,999 + GST
+ Govt. fee and stamp duty at actual
Fee confirmed in writing before you pay
What you'll get
Most Popular
New LLPs that will bill clients and need GST from day one
₹4,499 + GST
+ Govt. fee and stamp duty at actual
Fee confirmed in writing before you pay
What you'll get
Partners who want registration plus the first year's MCA filings handled
₹6,999 + GST
+ Govt. fee and stamp duty at actual
Fee confirmed in writing before you pay
What you'll get
Government fees and taxes are extra where applicable. Our expert confirms the final amount on the first call. No hidden charges.
LLP registration is the legal process of forming a Limited Liability Partnership with the Ministry of Corporate Affairs (MCA) under the Limited Liability Partnership Act, 2008. Once the Registrar approves your FiLLiP form, the LLP becomes a body corporate. It gets its own name, LLPIN, PAN and TAN. Partners keep the freedom of a partnership, but their personal assets are protected from the business debts of the LLP.
An LLP suits professionals, consultants, agencies, traders and family businesses that want limited liability without the heavier rules of a company. The whole process is online. You reserve a name through RUN-LLP, file the incorporation form FiLLiP, and then file the LLP agreement in Form 3 within 30 days. No office visit is needed.
TaxCaller has helped business owners with registrations and tax work since 2018. Our tax experts prepare your documents, draft the LLP agreement, file every form and answer Registrar queries until the certificate is issued. Our head office is in New Delhi, and we handle LLP registration for clients across India.
Complete guide
Choose a topic to open it. Every answer gives the rule or section it comes from.
01 Topic 1 of 22
A Limited Liability Partnership is a mixed form of business. It joins the internal freedom of a partnership with the legal shield of a company. Section 3 of the LLP Act, 2008 says an LLP is a body corporate, separate from its partners. It has perpetual succession, so a change in partners does not end it.
A firm under the Indian Partnership Act, 1932 is not separate from its partners. Every partner is jointly and personally liable for all firm debts. An LLP removes that personal risk. In return, it must register with the MCA, keep proper books and file yearly returns. If you only need a low-cost firm, see our partnership firm registration page.
The main law is the LLP Act, 2008, read with the LLP Rules, 2009. The LLP (Amendment) Act, 2021 came into force on 1 April 2022. It brought in small LLPs, start-up LLPs and civil penalties in place of many criminal offences. You can read the Act and forms on the official MCA portal.
Next: Who Should Register an LLP, and Is It the Right Choice? →
02 Topic 2 of 22
No law forces a business to become an LLP. Registration is a choice you make when you want limited liability and a separate legal identity. It becomes the practical choice in these cases:
Clear answers here make the LLP agreement quick to draft and reduce disputes later.
Our company registration page compares every structure side by side. If you are still unsure, book a call. Our expert will help you pick the structure before you spend anything.
Zubair Company Registration Expert
Have a question on this topic? Ask Zubair on a free call.
← Previous Next: Types of LLP and Eligibility Requirements →
03 Topic 3 of 22
The Act has one registration route for all LLPs. It does, however, treat some LLPs differently for fees and penalties. Knowing your category helps you plan costs.
| Category | What it means | Why it matters |
|---|---|---|
| Small LLP | Section 2(1)(ta): contribution up to ₹25 lakh and turnover up to ₹40 lakh in the previous year. The Government can raise these by rules, up to ₹5 crore and ₹50 crore. | Lower late fees and half penalties under Section 76A |
| Start-up LLP | An LLP recognised as a startup under the Central Government's startup notification | Half penalties under Section 76A |
| Other LLP | Every LLP that is not small or start-up | Normal fees and penalties |
| LLP with foreign partners | Non-resident individuals or foreign companies as partners | FEMA rules and RBI reporting apply to their contribution |
| Converted LLP | A firm or company that becomes an LLP under Sections 55 to 58 | Assets, contracts and staff move to the LLP |
Foreign individuals and foreign companies can be partners in an Indian LLP. Foreign investment in an LLP is allowed under the automatic route only in sectors where the FDI policy permits 100% foreign investment without performance conditions. The contribution must come through normal banking channels and be reported to the RBI under FEMA. At least one designated partner must still be resident in India. We check the sector rules before filing, because a wrong sector can block the bank from accepting the money.
| Event | Form | Time limit |
|---|---|---|
| Capital contribution or profit share bought by a non-resident | Form LLP(I) | Within 30 days of receiving the money |
| Transfer of contribution or profit share between a resident and a non-resident | Form LLP(II) | Within 60 days of receipt of funds |
| Foreign contribution outstanding on 31 March | FLA return | By 15 July every year |
The LLP files Form LLP(I). For Form LLP(II), the duty to report lies on the resident transferor or transferee. Both go on the RBI FIRMS portal through the bank, under Regulation 4 of the Foreign Exchange Management (Mode of Payment and Reporting of Non-Debt Instruments) Regulations, 2019. Schedule VI of the FEM (Non-debt Instruments) Rules, 2019 sets the investment conditions. A late report attracts a late submission fee.
04 Topic 4 of 22
For most service businesses and partner-led firms, the benefits outweigh these limits. If outside funding is likely in the next two years, talk to us about a company first.
← Previous Next: LLP vs Partnership Firm vs Private Limited Company →
05 Topic 5 of 22
An LLP sits between a partnership firm and a company. It gives limited liability like a company, with the internal freedom of a firm. The table shows the main differences.
| Point | Partnership firm | LLP | Private limited company |
|---|---|---|---|
| Law | Indian Partnership Act, 1932 | LLP Act, 2008 | Companies Act, 2013 |
| Registration | With the state Registrar of Firms; optional, but an unregistered firm cannot sue third parties to enforce contracts (Section 69) | Compulsory with the MCA | Compulsory with the MCA |
| Separate legal entity | No | Yes | Yes |
| Liability of owners | Unlimited and joint | Limited to agreed contribution, except for own wrongful acts | Limited to unpaid share capital |
| Members | 2 to 50 partners | Minimum 2 partners, no maximum | 2 to 200 members |
| Yearly MCA filings | None | Form 11 and Form 8 | AOC-4, MGT-7 or MGT-7A, plus board meetings and AGM |
| Statutory audit | Only tax audit, where it applies | Only above the Rule 24(8) limits | Every year, whatever the size |
| Income tax | 30% plus surcharge and cess | 30% plus surcharge and cess | Can choose a lower concessional rate; dividends taxed again in shareholders' hands |
| Raising equity | Not possible | Not by shares; new partners bring contribution | Shares, ESOPs and investor rounds |
| Change into another form | Can convert into an LLP (Section 55) | Can convert into a company (Companies Act, Section 366) | Can convert into an LLP (Section 56) |
For most growing businesses, yes. The partners' homes and savings are protected, the business can own assets in its own name, and it continues when partners change. The cost is yearly MCA filing. A small, low-risk firm run by family members may still find a registered firm cheaper. See partnership firm registration for that route, or Private Limited Company registration if investors are likely.
Abhinay Rai Company Registration Expert
Have a question on this topic? Ask Abhinay on a free call.
06 Topic 6 of 22
For income tax, an LLP is treated like a partnership firm. From 1 April 2026, the Income-tax Act, 2025 took the place of the 1961 Act. Income of tax year 2026-27 onwards falls under the new Act. Income of financial year 2025-26 and earlier years is still assessed under the Income-tax Act, 1961.
| Item | How it works |
|---|---|
| Tax rate | 30% of total income |
| Surcharge | 12% of the tax, only if total income is above ₹1 crore |
| Health and education cess | 4% of tax plus surcharge |
| Partner's share of profit | Exempt in the partner's hands, because the LLP has already paid tax on it |
| Salary, bonus or commission to working partners | Deductible for the LLP within the limits in the Act, only if the LLP agreement allows it. The partner pays tax on it as business income. |
| Interest on partner's capital | Deductible up to 12% a year simple interest if the agreement allows it (section 40(b) of the 1961 Act, section 35 of the 2025 Act) |
| Presumptive tax scheme | Not available to an LLP: section 44AD of the 1961 Act and section 58 of the 2025 Act both exclude it |
| TDS on payments to partners | 10% when salary, bonus, commission or interest paid or credited to a partner goes above ₹20,000 in total. This started under section 194T of the 1961 Act from 1 April 2025 and now sits in section 393 of the 2025 Act. |
| Yearly tax return | ITR-5, filed every year even when there is no income |
Salary to working partners is deductible only within a formula. Under section 40(b) of the 1961 Act, and section 35 of the 2025 Act from tax year 2026-27, the limit is the higher of ₹3 lakh or 90% of the first ₹6 lakh of book profit, plus 60% of the balance. Interest on capital is allowed up to 12% a year. Payments above these limits are added back to the LLP's income.
The way the agreement is written changes the tax bill. A clause that authorises partner salary and interest can lower the LLP's taxable profit legally. A missing clause means those payments are not deductible at all. This is why we draft the agreement with the tax position in mind.
Because the new Act renumbered most provisions, we always confirm the section that applies to the year being filed. Our income tax filing and TDS return filing teams handle these returns after registration. You can also check details on the Income Tax e-filing portal.
07 Topic 7 of 22

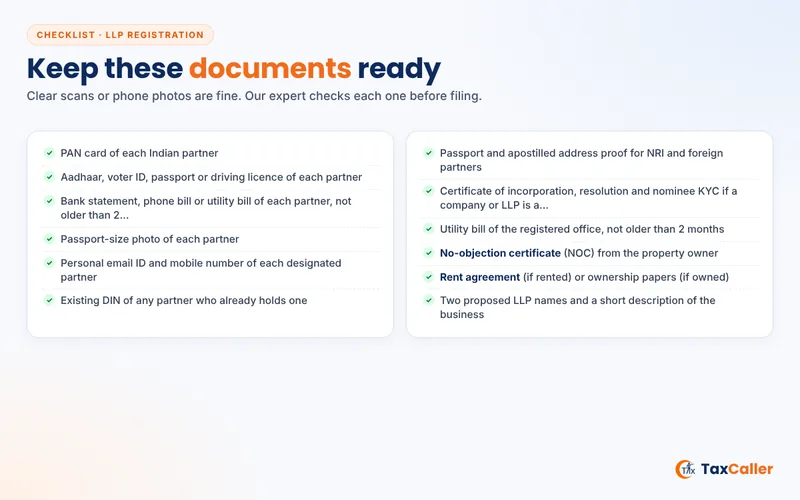
Most delays come from documents that do not match. Names, dates of birth and addresses must be the same on PAN, Aadhaar and the DSC. Use this checklist before you start.
| For whom | Documents |
|---|---|
| Each Indian partner | PAN card; Aadhaar, voter ID, passport or driving licence; a bank statement, phone bill or utility bill not older than two months; passport-size photo; personal email and mobile number |
| Foreign national or NRI partner | Passport; address proof such as a bank statement, residence card or utility bill; documents notarised and apostilled (or consularised) in the home country; photo |
| Company or LLP as a partner | Certificate of incorporation; board or partners' resolution naming the nominee; KYC of the nominee |
| Registered office | Electricity, water, gas or phone bill not older than two months; NOC from the owner; rent agreement if rented, or ownership papers if owned |
| Shared or co-working office | Allotment letter or service agreement, NOC from the operator and a recent utility bill of the premises |
| The proposed LLP | Two name options; main business activity; contribution of each partner; profit sharing ratio; details of other companies or LLPs where partners hold office |
| Special cases | Trademark owner's NOC if the name uses a mark; regulator approval for restricted words; existing firm or company papers if you are converting |
We send you a personalised checklist on the first call. You upload scans online; no courier or office visit is needed for an Indian partner.
← Previous Next: Choosing an LLP Name: Section 15 and RUN-LLP →
08 Topic 8 of 22
The name is the first thing the Registrar checks. Section 15 requires every LLP name to end with "Limited Liability Partnership" or "LLP". The LLP Rules list names that cannot be allowed.
RUN-LLP (Reserve Unique Name) is a short web form on the MCA portal. You can propose two names and explain their meaning. The fee is ₹200. If the Registrar raises a query, you get 15 days to resubmit. An approved name stays reserved for about three months (90 days), so you must file FiLLiP within that time. You can also reserve the name inside FiLLiP itself, but a rejected name then holds up the full application.
If an approved name later turns out to be too similar to another, Section 17 lets the Central Government direct a change. Since the 2021 amendment, if the LLP does not comply, the Government can allot a new name itself.
Shadab Company Registration Expert
Have a question on this topic? Ask Shadab on a free call.
← Previous Next: DSC, DIN and DPIN for Designated Partners →
09 Topic 9 of 22
Three terms confuse most first-time founders. Here is what each one means and who needs it.
| Item | What it is | Who needs it |
|---|---|---|
| DSC | A Class 3 digital signature certificate issued by a licensed certifying authority under the IT Act, 2000. It is used to sign MCA forms online. | Every designated partner who signs FiLLiP and later forms |
| DIN | Director Identification Number allotted by the MCA. One person gets one DIN for life. | Every designated partner |
| DPIN | Designated Partner Identification Number. Under the LLP Rules, the DIN is used as the DPIN. | Same as DIN; no separate number is issued |
FiLLiP can allot a DIN to designated partners who do not have one. Since the LLP (Second Amendment) Rules, 2022, up to five individuals can apply for a DIN in one FiLLiP. A designated partner added after incorporation applies for a DIN separately, and the LLP files Form 4 within 30 days.
A DSC is issued after online identity checks, usually Aadhaar-based or PAN-based with a short video. It normally takes one to two working days. Validity is usually one or two years. Keep the token safe, because you will need it for Form 3, Form 8 and Form 11.
A DIN holder must file DIR-3 KYC Web. From 31 March 2026, this is once every three financial years, by 30 June. If it is missed, the DIN is deactivated until KYC is filed with a ₹5,000 fee. Partners who are not designated partners do not need a DIN. They sign the subscription sheet and the LLP agreement.
← Previous Next: LLP Registration Process: How TaxCaller Files It Online →
10 Topic 10 of 22

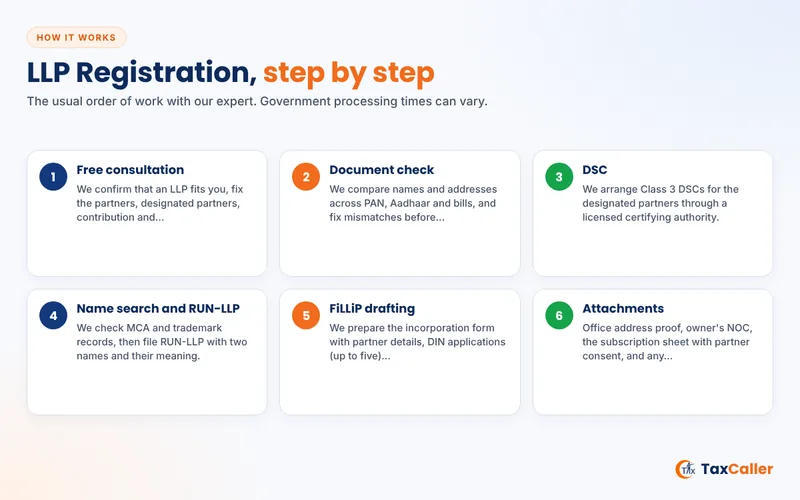
Here is the full process we follow for every client. You only need to upload documents, sign where asked and approve the drafts.
Section 12 of the Act says the Registrar shall register the LLP within 14 days of a complete filing. Most clean applications are approved well within that time.
← Previous Next: Can You Register an LLP Yourself, or Do You Need a CA? →
11 Topic 11 of 22
Yes, partners can start the filing themselves on the MCA portal, but the law still needs a professional in one place. Section 11(1)(c) of the LLP Act requires a statement that all legal requirements are met. It is made by an advocate, Chartered Accountant, Company Secretary or Cost Accountant engaged in forming the LLP, and also by one of the subscribers. So a CA is not compulsory, but one of these four professionals is.
A false statement in the incorporation papers is an offence under Section 11(3), so the professional who signs must actually check your papers. That is the job our tax experts do, with the statement signed by a practising professional.
Shreya Company Registration Expert
Have a question on this topic? Ask Shreya on a free call.
← Previous Next: The LLP Agreement: Contents, Stamp Duty and Form 3 →
12 Topic 12 of 22
The LLP agreement is the rulebook of your business. Section 23 says the mutual rights and duties of partners are governed by it. If there is no agreement, or it is silent on a point, the First Schedule of the Act applies by default (Section 23(4)).
Under the First Schedule, all partners share capital, profits and losses equally. No partner is entitled to any salary. A majority cannot expel a partner unless the agreement gives that power. These defaults rarely match what partners actually intend, so a written agreement is important.
The agreement must be printed on non-judicial stamp paper, or e-stamp paper, of the state where the registered office is located. The amount is set by that state's stamp law and often depends on the contribution. We tell you the exact figure for your state before you buy the paper.
Section 32 lets a partner contribute money, movable or immovable property, a promissory note or an agreement to contribute cash or property, or services. The value of each partner's contribution must be shown in the LLP's accounts. Cash contribution is ideally deposited into the LLP's bank account, so there is a clear record. Contribution in kind needs a fair value, often supported by a valuation report.
Under Rule 21(1) of the LLP Rules, Form 3 must be filed within 30 days of incorporation. The same form is used for every later change in the agreement, again within 30 days of the change. If contribution rises into a higher slab, the extra registration fee is also paid through Form 3. A late Form 3 attracts an additional fee of up to 50 times the normal fee, so we file it in the first week where possible.
← Previous Next: How Long LLP Registration Takes: Stage-wise Timeline →
13 Topic 13 of 22
Most LLPs are registered in about 10 to 15 working days from the day we receive complete documents. The table shows where the time goes.
| Stage | Usual time | What decides it |
|---|---|---|
| Document check and DSC | 1 to 2 working days | Clear scans and quick video verification |
| Name approval through RUN-LLP | 2 to 5 working days | Registrar workload; a query adds time |
| Drafting and signing FiLLiP | 1 to 2 working days | Partners signing with DSC promptly |
| Registrar approval of FiLLiP | Up to 14 days by law (Section 12) | Accuracy of attachments; resubmission if queried |
| PAN and TAN | Issued with the certificate | Automatic through FiLLiP |
| LLP agreement and Form 3 | Within 30 days of incorporation | Stamp paper purchase and partner signatures |
| Current account | Depends on the bank | The bank's own KYC checks |
The Registrar's time is outside anyone's control, so no firm can honestly promise a fixed day. What we can control is our side. We draft forms the same day documents arrive, file RUN-LLP and FiLLiP back to back, and reply to queries quickly. Clean documents are the biggest factor in speed.
We update you at every stage on WhatsApp and email, so you always know what is pending and with whom.
14 Topic 14 of 22

These amounts are paid to the government or to third parties. They are not part of TaxCaller's fee. We pay them on your behalf at actual and share every receipt. The MCA fees below come from Annexure A of the LLP Rules, as revised by notification G.S.R. 109(E) with effect from 1 April 2022.
| Item | Official amount |
|---|---|
| Name reservation through RUN-LLP | ₹200 |
| FiLLiP, contribution up to ₹1 lakh | ₹500 |
| FiLLiP, above ₹1 lakh up to ₹5 lakh | ₹2,000 |
| FiLLiP, above ₹5 lakh up to ₹10 lakh | ₹4,000 |
| FiLLiP, above ₹10 lakh up to ₹25 lakh | ₹5,000 |
| FiLLiP, above ₹25 lakh up to ₹1 crore | ₹10,000 |
| FiLLiP, above ₹1 crore | ₹25,000 |
| Form 3 and other forms, by contribution | ₹50 (up to ₹1 lakh), ₹100, ₹150, ₹200, ₹400, up to ₹600 (above ₹1 crore) |
| Form 4 (change in partners) | ₹50 for a small LLP, ₹150 for others |
| Stamp duty on the LLP agreement | As per the state stamp law |
| DSC for each designated partner | Charged by the certifying authority |
| Notary and apostille for foreign papers | At actual, in the partner's country |
Take two partners with a total contribution of ₹1 lakh. The MCA fees are ₹200 for the name, ₹500 for FiLLiP and ₹50 for Form 3. That is ₹750 in total. Stamp duty for your state and the DSCs are added to this. Fees are collected on the MCA portal at the time of filing, so the portal amount always prevails.
A few small costs are not government fees but are still outside our professional fee. These include the DSC charge of the certifying authority, the stamp vendor's service charge, notary charges and courier costs for foreign documents. We list each one in your quote, so the final bill holds no surprises.
Contribution drives the fee. Many founders start with a modest contribution and increase it later through Form 3, paying the slab difference then.
Zubair Company Registration Expert
Have a question on this topic? Ask Zubair on a free call.
15 Topic 15 of 22
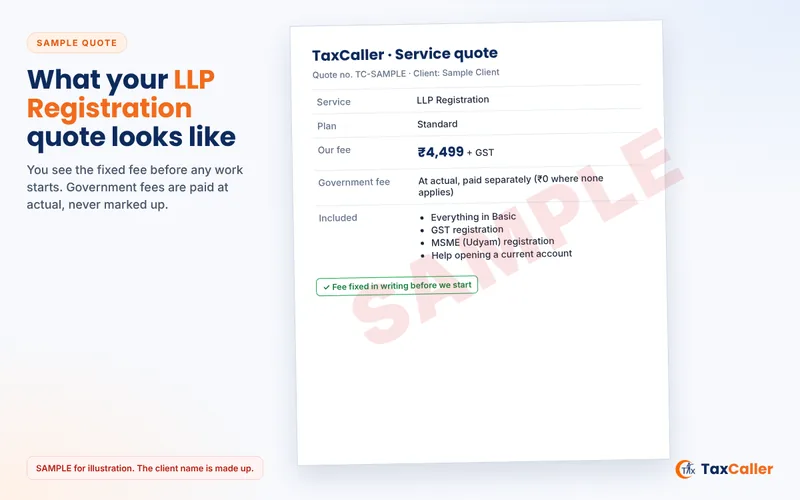
TaxCaller's fee covers our professional work only. TaxCaller's fee starts at ₹2,999 + GST for the Basic plan. Government fees (RUN-LLP fee, FiLLiP fee, Form 3 fee and stamp duty) are paid separately at actual. Nothing is added later without your approval.
| Plan | What is included |
|---|---|
| Basic | Name approval, DSC applications for 2 designated partners (DSC charges extra), DIN through FiLLiP, FiLLiP filing, certificate with LLPIN, PAN and TAN, LLP agreement drafting and Form 3 filing |
| Standard | Everything in Basic, plus GST registration, MSME (Udyam) registration and help opening a current account |
| Premium | Everything in Standard, plus first-year Form 11 and Form 8 filing and a compliance calendar |
Each plan's price is shown in the pricing cards on this page, and each is + GST.
In these cases our expert confirms the final amount on the first call, in writing. Yearly bookkeeping, audit support and tax returns are separate services. See accounting and bookkeeping for that.
← Previous Next: Annual Compliance After Registration: Form 11, Form 8, ITR and Audit →
16 Topic 16 of 22
Registration is the start. Every LLP must file certain returns each year, even if it did no business. Missing them builds late fees quickly.
| Filing | Form | Due date | Legal basis |
|---|---|---|---|
| Annual return | Form 11 | 30 May (within 60 days of the year end) | Section 35, Rule 25 |
| Statement of account and solvency | Form 8 | 30 October (within 30 days after six months of the year) | Section 34, Rule 24 |
| Income tax return | ITR-5 | As per the Income-tax Act; a later date applies when audit is required | Income-tax Act |
| Director KYC of designated partners | DIR-3 KYC Web | Once every three financial years, by 30 June | G.S.R. 943(E) |
| Change in partners or designated partners | Form 4 | Within 30 days of the change | Section 25 |
| Change in LLP agreement | Form 3 | Within 30 days of the change | Rule 21 |
| Change of registered office | Form 15 | Within 30 days of the change | Section 13, Rule 17 |
Rule 24(8) of the LLP Rules says an LLP whose turnover does not exceed ₹40 lakh, or whose contribution does not exceed ₹25 lakh, in a financial year need not get its accounts audited. Read literally, the audit is needed only when both limits are crossed. Some professionals advise an audit once either limit is crossed, and many banks ask for audited accounts anyway. The audit must be done by a Chartered Accountant in practice. A separate tax audit applies when turnover crosses the Income-tax Act limit.
The LLP must keep proper books on a cash or accrual basis at its registered office. Rule 24 requires them to be preserved for eight years. GST returns and TDS returns also apply once the LLP is registered under those laws. Our GST return filing and bookkeeping teams can take this over from day one.
An LLP that has not carried on business for a year or more can apply to be struck off in Form 24, under Section 75 and Rule 37. The government fee is ₹500 for a small LLP and ₹1,000 for others. All pending Form 8 and Form 11 filings must be completed first, and the bank account should be closed. From 27 August 2024, these applications are processed by the Centre for Processing Accelerated Corporate Exit (C-PACE), under notification G.S.R. 475(E).
17 Topic 17 of 22
Since the 2021 amendment, most LLP defaults carry civil penalties instead of criminal cases. The adjudicating officer, usually the Registrar, imposes them under Section 76A. The table lists the ones new LLPs meet most often.
| Default | Consequence | Legal basis |
|---|---|---|
| Form 11 filed late | Additional fee on the portal; the adjudicating officer may also levy a penalty of ₹100 a day, up to ₹1 lakh for the LLP and ₹50,000 for each designated partner | Section 35, Annexure A |
| Form 8 filed late | Additional fee on the portal; the adjudicating officer may also levy a penalty of ₹100 a day, with the same caps | Section 34, Annexure A |
| Form 3 or Form 4 filed late | Additional fee from 1 time to 50 times the normal fee (up to 25 times for a small LLP) | Annexure A, LLP Rules |
| False statement in the incorporation papers | Punishable under Section 11(3), for the person who signs knowing it is false | Section 11(3) |
| Fewer than two partners for over six months | The remaining partner is personally liable for obligations of that period | Section 6(2) |
| No resident designated partner, or fewer than two | The vacancy must be filled; penalty for continuing default | Sections 7 to 10 |
| DIR-3 KYC not filed | DIN deactivated; ₹5,000 fee to reactivate | Director KYC rules |
| Business carried on to defraud creditors | Unlimited liability for the LLP and persons involved; imprisonment up to five years and fine | Section 30 |
| Penalty order not followed within 90 days | LLP: fine of ₹25,000 to ₹5 lakh. Partner: up to six months' jail, a fine of ₹25,000 to ₹1 lakh, or both | Section 76A(8) and (9) |
For Form 8 and Form 11, the additional fee starts at the normal fee for up to 15 days of delay. For an LLP that is not small, it rises to 4, 8, 12, 20 and then 30 times the normal fee as the delay crosses 15, 30, 60, 90 and 180 days. After 360 days, ₹20 is added for every further day. A small LLP pays half these multiples, and ₹10 a day after 360 days.
Under the proviso to Section 76A(3), no penalty applies for certain Form 8 and Form 11 defaults that are fixed before the officer's notice, or within 30 days of it. Small LLPs and start-up LLPs pay half the penalty, with lower caps. The additional fee is still payable. The cheapest route is simply to file on time.
Abhinay Rai Company Registration Expert
Have a question on this topic? Ask Abhinay on a free call.
← Previous Next: Common Mistakes and FiLLiP Rejection Reasons →
18 Topic 18 of 22
Most rejections and resubmissions come from a short list of avoidable errors. We check each of these before filing.
If a query is raised, the Registrar gives a set time to resubmit. We reply on the same day where possible, so your name reservation does not lapse.
19 Topic 19 of 22
You do not have to close an existing business to become an LLP. The Act gives three conversion routes, and each keeps your assets and contracts intact.
| From | Law | Form | Main condition |
|---|---|---|---|
| Partnership firm | Section 55, Second Schedule | Form 17 with FiLLiP | All partners of the firm, and no one else, become partners of the LLP |
| Private company | Section 56, Third Schedule | Form 18 with FiLLiP | All shareholders, and no one else, become partners; no security interest is pending, or the holders agree |
| Unlisted public company | Section 57, Fourth Schedule | Form 18 with FiLLiP | Same conditions as a private company |
Conversion can be tax-neutral, but only when the conditions in the income tax law are met. These cover turnover, total assets, profit-sharing ratios and holding periods. We review them before you file, because a failed condition can create capital gains tax.
An LLP can also become a company under Section 366 of the Companies Act, 2013. This is common when investors join. See our Private Limited Company registration page for that route.
20 Topic 20 of 22
These are the official changes that affect an LLP formed or running in 2026. We follow the rules in force today and update this page when the MCA notifies new ones.
The Companies (Appointment and Qualification of Directors) Amendment Rules, 2025, notified as G.S.R. 943(E) on 31 December 2025, took effect on 31 March 2026. Every DIN holder, including designated partners of LLPs, now files DIR-3 KYC Web once every three financial years, by 30 June. The old yearly filing has ended. Changes in mobile number, email or address still need a prompt update.
Notification S.O. 4849(E), dated 23 October 2025 under Section 68A of the LLP Act, reorganised the Registrars that handle LLPs. Its start date was moved from 1 January 2026 to 16 February 2026 by S.O. 6113(E), dated 30 December 2025. From the same date, S.O. 696(E) names these Registrars as adjudicating officers under Section 76A. Uttar Pradesh now has two LLP Registrars, at Kanpur and Noida, and Delhi has two. Your Registrar depends on the district of your registered office.
The new Act uses "tax year" in place of previous year and assessment year. An LLP is still taxed like a firm at 30% plus surcharge and cess. TDS on partner salary and interest, earlier section 194T, now falls under section 393. The 1961 Act still governs returns for financial year 2025-26.
The Bill was introduced in the Lok Sabha on 23 March 2026 and sent to a Joint Parliamentary Committee, which reported on 3 August 2026. For LLPs it proposes rules for LLPs in IFSCs, conversion of certain trusts into LLPs, registered valuers, and more civil penalties in place of offences. It has not been passed. Until it becomes law, the current LLP Act applies in full.
The Companies Compliance Facilitation Scheme, 2026 and the October 2026 fee waivers in General Circulars 05/2026 and 06/2026 apply to company forms. They do not cover LLP forms. A new LLP should therefore plan its first Form 3, Form 11 and Form 8 on the normal dates.
The fee table of 2022, the 30-day Form 3 deadline, the Form 11 and Form 8 due dates and the audit limits under Rule 24(8) remain the same in 2026. You can confirm notifications in the e-Gazette of India.
Shadab Company Registration Expert
Have a question on this topic? Ask Shadab on a free call.
← Previous Next: LLP Registration in Ghaziabad, Delhi NCR and Other States →
21 Topic 21 of 22
The process is the same across India, because every form is filed on the MCA portal. Two things change with your state: the Registrar who approves you, and the stamp duty on your agreement.
From 16 February 2026, LLPs with a registered office in western UP fall under the Registrar of Companies, Uttar Pradesh-II, at Noida. Its districts include Ghaziabad, Gautam Buddha Nagar, Meerut, Hapur, Bulandshahr, Baghpat, Agra, Aligarh and Mathura. LLPs in Lucknow, Kanpur, Varanasi, Prayagraj and other districts fall under Uttar Pradesh-I, at Kanpur.
Delhi now has two LLP Registrars. Delhi-I covers South, South West, New Delhi, South East and East districts. Delhi-II covers Central, West, North, North West, North East and Shahdara districts.
Maharashtra and West Bengal also have more than one LLP Registrar after the 2025 notification. In every state, stamp duty on the LLP agreement follows the local stamp law, and many states offer e-stamp paper.
Your Registrar approves the name and FiLLiP, raises queries, and acts as the adjudicating officer for penalties under Section 76A. Notices for late Form 8 or Form 11 also come from that office. Knowing the right office helps you reply in time and to the right place. We track Registrar notices for our clients and reply within the time given.
A move within the same city needs only Form 15. A move to another state also changes your Registrar, so plan it with your expert. Our head office is in New Delhi, and we register LLPs online for clients in every state.
22 Topic 22 of 22
Have a question first? Contact us or book a free call using the form on this page.
Don't have everything? Send what you have on WhatsApp. Our expert will tell you what's missing.
Send documents on WhatsAppReal experts, not a call centre
Your work is handled by experienced professionals who explain every step, check your documents and keep you updated.
Registered company
TaxCaller is run by TaxCaller India LLP (LLPIN AAQ-7388), serving clients since 2018.
Fee told upfront
You know the complete fee, our professional fee and the government fee, before any work starts. No hidden charges.
Support after the work
Notices, renewals, returns and compliance reminders: we stay with your business after the registration is done.
Expert for this topic LLP Registration
Abhinay Rai
Advocate
Abhinay Rai is a Advocate specialising in LLP Registration. The process, documents, timelines and fees on this page are checked against the current rules and government portals, and updated whenever the law, forms or fees change.
LLP registration is the process of forming a Limited Liability Partnership with the MCA under the LLP Act, 2008. It is not mandatory for any business. You choose it when partners want limited liability and a separate legal identity. Once registered, the LLP gets an LLPIN, PAN and TAN, and it must file yearly returns.
The total cost has two parts. Government fees include ₹200 for the name, a FiLLiP fee from ₹500 based on contribution, the Form 3 fee and state stamp duty. DSCs are charged separately. TaxCaller's professional fee is shown in the plans on this page and is charged + GST. We confirm your total on the first call.
Most LLPs are registered in about 10 to 15 working days once documents are complete. DSC takes one to two days, name approval two to five days, and the Registrar has up to 14 days for FiLLiP under Section 12. The LLP agreement is then filed in Form 3 within 30 days of incorporation.
There is no minimum capital or contribution for an LLP. Partners can agree any amount in cash, property or services. The contribution does affect your costs, because the FiLLiP fee, the Form 3 fee and often the stamp duty rise with it. Many founders start small and increase contribution later through Form 3.
No. Section 6 of the LLP Act needs at least two partners, and the LLP must have two designated partners. If an LLP keeps only one partner for more than six months, that partner becomes personally liable for that period. A single founder who wants limited liability should look at a One Person Company instead.
Yes. An NRI, a foreign national or a foreign company can be a partner. At least one designated partner must be resident in India, meaning a stay of 120 days or more in the financial year. Foreign contribution must follow FEMA rules and be reported to the RBI. Foreign documents must be apostilled or consularised.
No. Rule 24(8) of the LLP Rules says an LLP need not be audited if its turnover does not exceed ₹40 lakh, or its contribution does not exceed ₹25 lakh, in that year. Once both limits are crossed, a Chartered Accountant in practice must audit the accounts. A tax audit may also apply separately.
Yes, in practice. If there is no agreement, the First Schedule applies, so partners share profits equally and get no salary. The agreement must be filed in Form 3 within 30 days of incorporation under Rule 21. A late filing attracts an additional fee that can reach 50 times the normal fee.
You can file the forms yourself on the MCA portal, but Section 11(1)(c) of the LLP Act needs a compliance statement from an advocate, Chartered Accountant, Company Secretary or Cost Accountant engaged in the formation. So a CA is not compulsory, but one of these professionals is. Most founders use one to avoid queries and rejection.
Yes. A residential address can be the registered office. You need a recent utility bill not older than two months and a no-objection letter from the owner. If the house is rented, attach the rent agreement too. Under Section 13, the office must be able to receive official letters and notices.
Not automatically. An LLP needs GST registration when its turnover crosses the GST threshold, or when it makes inter-state supply of goods, sells through e-commerce operators or falls in another compulsory category. Many LLPs register voluntarily to claim input tax credit and to work with larger clients. We can file it right after incorporation.
For most growing businesses, yes. An LLP is a separate legal entity, so partners are not personally liable for its debts, and it continues when partners change. A partnership firm costs less and has no MCA filings, but every partner carries unlimited liability. If investors are likely, a Private Limited Company may suit you better than either.
Yes. Section 55 and the Second Schedule of the LLP Act allow a firm to convert by filing Form 17 with FiLLiP. All partners of the firm, and no one else, must become partners of the LLP. Assets, contracts and cases move to the LLP, and the firm is treated as dissolved.
Every designated partner is a partner, but not every partner is a designated partner. Designated partners must be individuals with a DIN and DSC, and they are responsible under Section 8 for filings, returns and penalties. Other partners share profits and decisions under the agreement but carry fewer statutory duties. An LLP needs at least two designated partners.
The LLP must still file Form 11 by 30 May, Form 8 by 30 October and its income tax return every year. Late fees apply even with nil activity. If you have no plans to use it, you can apply to close it in Form 24, after filing pending returns and closing the bank account.
Book a free call to confirm your total cost before you pay anything. TaxCaller's fee starts at ₹2,999 + GST, and government fees are shown separately at actual.
Mon–Fri 9:00 AM – 6:00 PM, Sat 10:00 AM – 4:00 PM · Your trust is our biggest fee.